Subcontractor Prequalification: The Five Questions That Predict Default
Learn the five subcontractor prequalification questions that help predict default risk—from financial stability and past performance to safety, insurance, and staffing.
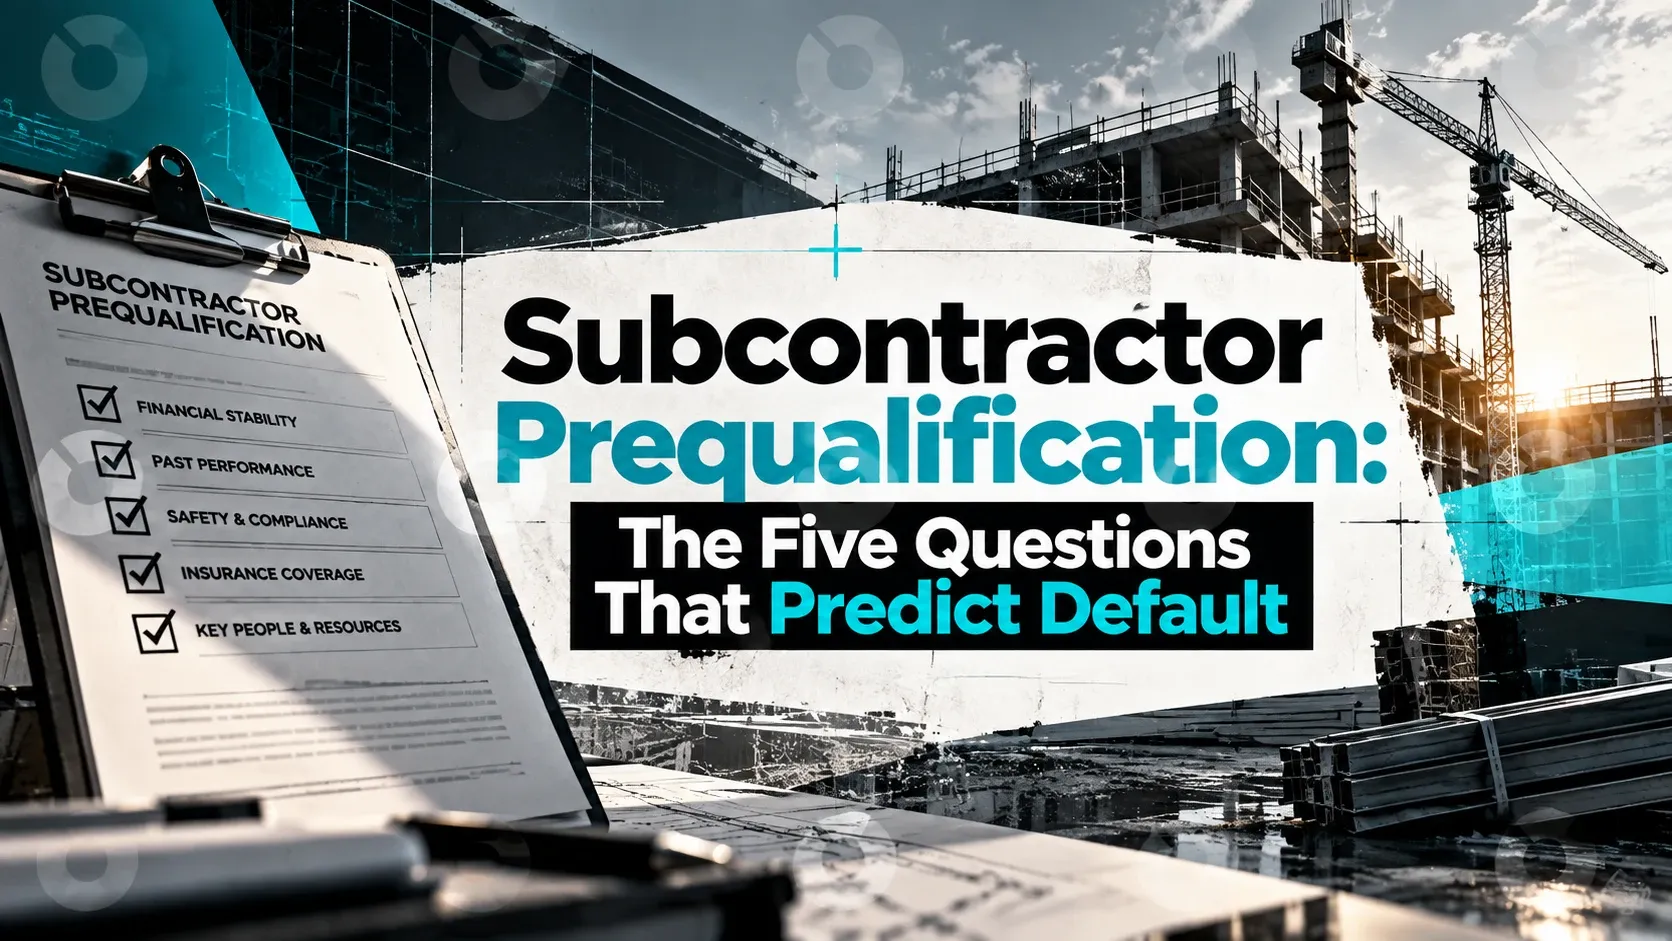
A subcontractor prequalification process is only useful if it measures current exposure rather than historical competence. The five questions that actually predict default are: backlog against bonding capacity, your project's size relative to the largest job the sub has ever completed, work-in-hand committed to other GCs, dependency on lower-tier subs and suppliers, and the age of the financial statement on file. Everything else is documentation.
Most prequal packages collect a stack of certificates, a signed safety manual, three references and a two-year-old balance sheet, then produce a score that correlates with how well the sub fills out forms. The subs that fail mid-job rarely fail the questionnaire. They fail because they took four other awards in the ninety days after you qualified them, and nobody looked again.
What should a subcontractor prequalification form actually ask
The form should produce numbers you can compare across trades and across time, not narrative answers that require a human to interpret. Group the questions into five sections and insist on dated figures for each.
Capacity and backlog. Total aggregate bonding capacity, single-project bonding capacity, current uncompleted contract value (backlog), and backlog as of what date. Ask for the surety's name and the underwriter's contact. The gap between aggregate capacity and current backlog is the sub's remaining room, and it is the single most predictive number on the form.
Project size history. The largest single project the firm has completed in the last three years, by contract value, with the owner and GC named. Then the largest currently in progress. If your scope is more than roughly 150 percent of the largest completed job, you are asking the sub to do something new, and the risk is operational, not financial.
Work-in-hand by customer. Current contracts in progress, listing GC, contract value, percent complete and scheduled completion. This is the section subs resist and the section that matters most. A sub with four jobs finishing in the same six-week window has a labor cliff coming whether or not they have told you.
Lower-tier dependency. What percentage of the sub's scope they self-perform versus buy out. Which lower-tier subs and suppliers they rely on for long-lead material. A glazing sub whose entire schedule is a single fabricator's shop capacity is exposed to a failure you cannot see in their financials.
Financial statements. Whether the statement is audited, reviewed or compiled, the preparer's name, and the period end date. A compiled statement for the year ended twenty months ago tells you almost nothing about their position today.
Safety and workforce. EMR by year for three years, OSHA 300A summaries, average field headcount, and the percentage of field labor that is direct-hire versus staffing agency. Safety history is also a labor-stability signal; a sub leaning heavily on agency labor has different turnover exposure than one with a stable direct crew, and contractor safety performance tracks closely with field supervision depth.
How to evaluate subcontractor financial capacity
Work from the balance sheet and the backlog schedule together. Neither one answers the question alone.
Start with working capital: current assets minus current liabilities. Compare it to the contract value you intend to award. A sub whose working capital is a small fraction of your contract value is funding your job out of someone else's payment cycle, and a single slow draw somewhere in their portfolio becomes your schedule problem.
Then look at the ratios that reveal how the balance sheet was built:
| Measure | What it tells you | Where it gets misread |
|---|---|---|
| Working capital | Cash available to carry labor and material before payment | A large receivable balance is not cash if the payer is slow |
| Current ratio | Short-term solvency cushion | Inflated by underbillings parked in current assets |
| Debt-to-equity | How much of the business is borrowed | Owner loans may sit in either column depending on the preparer |
| Underbillings (costs in excess of billings) | Work performed and not yet invoiced | Large or growing underbillings often mean unapproved change orders or billing disputes |
| Overbillings (billings in excess of costs) | Front-loaded cash position | Healthy in isolation, dangerous as a funding source for other jobs |
| Backlog to working capital | Whether the volume is supportable | Backlog figure is usually stale unless you demand a date |
Underbillings deserve particular attention. A line item that grows quarter over quarter usually means the sub is performing work that someone has not agreed to pay for. That dispute is already in their cash position, and it will reach yours.
Also ask who prepared the statement and whether the preparer issues the sub's bonds. A reviewed statement from a construction-specialist CPA carries different weight than a compiled statement from a general practice.
What is a reasonable single subcontractor bonding capacity limit
Sureties typically issue two numbers: a single-project limit and an aggregate limit. The single-project limit is the surety's own view of the largest job that firm can absorb, underwritten against their working capital, their track record and their management depth. Treat it as a ceiling someone with money at stake has already set.
Two practical rules follow. First, do not award a subcontract above the single-project limit on the assumption that the surety will stretch. They may, and the stretch tells you the surety is competing for business, not that the sub got stronger.
Second, aggregate capacity minus current backlog is the only real number. A sub with 40 million aggregate capacity and 36 million in backlog has four million of room regardless of what their single-project limit says. If your award is three million, you have just consumed most of their remaining capacity, and the next GC to call them will be told yes anyway.
Set internal thresholds by contract value band — which trades require bonding, which require a parent guarantee, which can proceed unsecured — and apply them consistently. Exceptions should be written down with the name of whoever approved them.
When to require a performance bond versus enrolling in subguard
The choice is between transferring the risk to a surety on a per-subcontract basis and retaining it inside a controlled default insurance program you administer.
| Factor | Performance bond | Subguard / CDI |
|---|---|---|
| Who underwrites the sub | The surety | You |
| Cost basis | Per subcontract, typically paid through the sub | Program-wide premium with a per-loss deductible |
| Who controls the replacement | Surety, under the bond's terms and timeline | You, immediately |
| Fit for small or emerging subs | Often unavailable — they cannot get bonded | Available if your own prequal clears them |
| Fit for sole-source or specialty scopes | Strong — the surety completes the work | Weaker — there may be no replacement to hire |
| Administrative load | Bond tracking, dual obligee riders, renewals | Prequal rigor, loss reserves, claim documentation |
Bond the scopes where replacement is slow and specialized: curtain wall, elevators, structural steel erection, anything with long-lead fabrication or a short bidder list. Use subguard where you have a deep bidder pool, you have real confidence in your own prequalification, and speed of replacement matters more than cost recovery.
The honest constraint on subguard is that it converts the surety's underwriting work into your underwriting work. If your prequal process is a filing exercise, you have retained the risk without acquiring the capability to price it.
Why prequalification has to be re-checked at award and during the job
A prequal is a snapshot of a company's position on the date the form was signed. By the time you award, that position has usually changed. Three triggers should force a re-check:
- At award. Confirm current backlog and remaining bonding capacity in writing. Ask what they have been awarded since they submitted. A one-page update, signed and dated, is enough.
- When committed value on your own projects doubles. If a sub carrying one two-million-dollar scope with you picks up two more, your aggregate exposure to that single firm changed materially even though each individual award passed its own threshold.
- On financial statement age. Anything older than twelve months at the point of award gets refreshed or the award gets conditions attached.
This is where most processes break operationally rather than conceptually. Prequal lives in a spreadsheet owned by one person in preconstruction. Awards live in the commitment log. Nobody runs the sum of committed value by vendor across active projects, so nobody notices that a sub qualified for three million is now carrying nine million of your work across four jobs.
Fixing it requires the prequal record and the commitment record to sit in the same system, where exposure by vendor is a report rather than a reconstruction. When contract values, change orders and pay application history for every subcontractor live in one connected platform, the question "what is our total committed value with this firm right now" takes a few seconds instead of a week of emails — which is exactly the kind of administrative recovery that construction administration platforms are built to deliver, and the same record that makes audit readiness a byproduct rather than a project.
Connecting prequalification to in-flight performance
Prequalification predicts; performance monitoring confirms. The firms that get the most from their prequal process feed outcomes back into it — schedule adherence, change order volume, rework, pay application accuracy, lien waiver compliance. A sub that scored well and then missed four milestones should score differently next time, and the scoring change should be automatic rather than remembered.
Tie the prequal score to the same dataset you use for contractor performance monitoring, and tie payment release to the same gate you use for lien waiver collection. A sub who is slow to return conditional waivers is telling you something about their back office, and their back office is where a default becomes visible first.
Platforms like INGENIOUS.BUILD hold the commitment, the change orders, the pay applications and the compliance documents for each subcontractor in a single record, which is what makes exposure-by-vendor a live number instead of a quarterly reconstruction. That is the difference between prequalification as a gate and prequalification as a position you manage.
Frequently asked questions
What should a subcontractor prequalification form ask that most forms miss?
Most forms miss three things: current backlog with a stated as-of date, work-in-hand broken down by general contractor, and the percentage of scope bought out to lower-tier subs. These reveal whether a firm has capacity right now. Certificates, safety manuals and references describe past competence, not present exposure.
How do you evaluate a subcontractor's financial capacity?
Read the balance sheet and the backlog schedule together. Compare working capital to your intended contract value, check whether underbillings are growing quarter over quarter, and confirm the statement's period end date and whether it is audited, reviewed or compiled. Growing underbillings usually signal unapproved change orders already in dispute.
What is a reasonable single-project bonding capacity limit for a subcontractor?
The surety's stated single-project limit is the practical ceiling, since the surety underwrote it against the firm's working capital and management depth. More important is aggregate capacity minus current backlog, which is the only remaining room the firm actually has, regardless of what the single-project number says.
When should a GC require a performance bond instead of using subguard?
Bond scopes where replacement is slow and specialized — curtain wall, elevators, structural steel erection, long-lead fabrication, short bidder lists — because the surety completes the work. Subguard fits deep bidder pools where speed of replacement matters more than cost recovery, but it shifts underwriting responsibility onto your own prequalification process.
How often should subcontractor prequalification be updated?
Re-confirm at award, refresh any financial statement older than twelve months, and re-run the review whenever committed value with that subcontractor across your active projects doubles. A prequal is a snapshot of one date; backlog and bonding room change within weeks of submission.
Why do prequalified subcontractors still default?
Because prequalification measures position on the date the form was signed. A firm that cleared your threshold can accept several other awards in the following months, consuming its remaining bonding capacity and labor. Without tracking aggregate committed value by vendor across active jobs, that accumulation is invisible until performance slips.